 arif-budianto
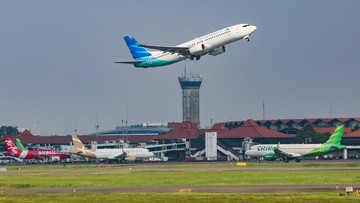
Menjelang musim→「libur panjang akhir tahun 2026/2027, regulators ioduida interest embarked on a two-track approach to menjaga affordability of air transportation. On one side, fiscal relief through the PPN DTP scheme applied to domestic scheduled flights; on the other side, adjustments to a range of non-fare components that airlines pass through to passengers. The combination, according to preliminary readings, is intended to prevent the customary seasonal price spike from turning into a permanent burden on household transport budgets.
Secara makro,背景 backdrop matters. Barth EPS volatility, a relatively wide range between the subsidised and non-subsidised fare classes, and a pass-through cost structure that includes fuel surcharge, airport charges, and insurance levies, all shape how much of the policy relief actually reaches the ticket buyer. Strikingly, the policy design reflects a core assumption of the economic team: that price elasticity of demand for domestic flights during Nataru remains high, meaning passengers respond sharply to fare differences between carriers and travel dates. That assumption is what makes a temporary tax break potentially powerful — and also what makes it fragile.
Mekanisme dan SKALA Insentif
The core instrument is the PPN DTP, or tax borne by the government rather than the airline. Operationally, the airline remits to the state a value-added tax that is then compensated, so the reported ticket price falls. For an average domestic fare in the mid-price band, an illustrative calculation shows the arithmetic: on a base fare of Rp1,4 juta, a fully passed-through 11% tax would represent roughly Rp154 ribu. If the compensation is absorbed entirely by the carrier, the ticket price declines by that amount — a reduction of about 11% relative to the undiscounted base.
It is important, however, to distinguish between headline fare reduction and total outlay reduction. Simulasi for a typical family of four travelling on a medium-haul domestic route shows that the combination of the tax break and calendar-based fare smoothing can keep total airfare spending in a range of Rp7,5 hingga Rp8,2 juta, versus a counterfactual of Rp8,8 hingga Rp9,6 juta if the full seasonal surge had materialised unchecked. Those figures are projections rather than official statistics, and they assume full pass-through of the incentive to consumers.
Pro dan Kontra: Dua Sisi dari Kebijakan Ini
Pro: From the demand side, the stimulus supports a sector where operating leverage is high — a seat that goes unsold generates zero revenue while still carrying fixed costs. Keeping fares accessible therefore protects load factor during the peak window, which in turn protects network economics for routes that would otherwise be marginal. Household-wise, air travel remains a discretionary but politically sensitive expenditure for middle-income earners, and easing the fare burden at year-end has a direct effect on consumption smoothing.
Kontra: The critical question is pass-through behaviour. If airlines absorb part of the incentive into margin rather than price, the headline promise weakens materially. Historically, sectors with concentrated supply and dynamic pricing have shown a measurable gap between announced reductions and observed ticket prices at the point of sale. Additionally, cost adjustments on the non-fare side partially offset the tax relief: even a 10% reduction in the tax component can be neutralised if fuel surcharge, airport service charges, and related levies rise in the same window.
Implikasi Makro dan Risiko Pelaksanaan
For the wider economy, the fiscal cost of the compensation scheme should be weighed against tourism and regional spending multipliers. A 1% increase in domestic air passenger volumes during Nataru does not translate one-for-one into GDP, but it does accelerate hotel occupancy, local transport ridership, and retail receipts in holiday destinations — categories where the multiplier is typically above one.
On the financial side, regulators such as the OJK and Bank Indonesia are watching a related transmission channel: consumer credit used for ticket purchases, and the effect of eased travel costs on household liquidity ratios at the end of the year. Liquidity-tight households are the group most sensitive to a fare spike, and the relief is proportionally most meaningful for them.
"Keterjangkauan tiketugnRestrictions isn't only about the fare printed on the itinerary. It's about the total amount a household needs to mobilise, including charges that are often overlooked at booking."
Three indicators will determine whether the policy achieves its objective. First, the actual ticket prices observed at the point of sale during the peak weeks, compared against the pre-policy baseline. Second, the proportion of the tax incentive that appears in consumer prices rather than carrier margins. Third, the behaviour of non-fare components, particularly fuel surcharge, which is tied to the international oil reference and the exchange rate and can move independently of domestic policy.
Ultimately, the policy should be judged on its bottom line: whether a family of four travelling domestically in December 2026 pays materially less than it would have without the stimulus. That test is simple, and it is the one that will shape investor and consumer sentiment in the aviation sector going into 2027.







Comments (0)