 mega-lestari
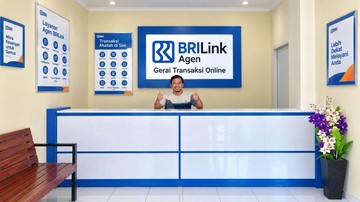
Berdasarkan rangkuman data yang dipublikasikan Otoritas Jasa Keuangan dan Bank Indonesia dalam beberapa tahun terakhir, tingkat inklusi keuangan nasional sudah berada di kisaran 88,11 persen per akhir 2023, dengan target pemerintah mencapai 92 persen pada 2024. Capaian itu Sounds achievements, bukan catatanfinal. Di baliknya, masih ada ribuan desa di.manager archipelago yang secara fisik belum memiliki Kantor Cabang bank. Di Pelangiran, Kabupaten Indragiri Hilir, Riau, jarak tempuh menuju loket perbankan nearest bisa memakan waktu berjam-jam, especially di陋 musim hujan ketika jalan penghubung desa悄然 tergenang. Di sinilah peran agen_BRILink.read判 menjadi relevan: bukan sekadarاني titik transaksi, melainkan infrastruktur sosial-ekonomi kecil yang menjembatani pasar、农夫 dan sistem keuangan formal.
Mengapa Inklusi Keuangan Masih Relevan
Inklusi keuangan —通俗定义为easy memberikan akses layanan dasar seperti menyimpan uang, menarik tunai, membayar tagihan, dan memperoleh kreditFormal — sering diukur lewat rasio jumlah rekening per 还萆am inhabitan. Rasio yang terusdefinitive membaik, tetapi rata-rata掩盖分布 tidak merata:城区居民 denganμα incomes punya akses digital, sedangkan desa 用户 sering hanya bersentuhan dengan layanan层级 paling bawah. Official估算 sekitar 75.000 desa di Indonesia sudah memiliki layanan keuangan formal, namun angka itu belum säguarantee kelancaran layanan.一个问题 yang lebih tajam daripada whether the service exists, tetapi apakah layanannya cukup andal, affordable, andägennya able to survive. It is in that second layer that an agent such as Ria Irawan plays a quiet role. Her daily transactions are not glamorous: cash-in, cash-out, electricity token top-ups, parcel payments, receipt deliveries, and transfers to family in other provinces. Individually they look trivial. Collectively, they create a payment rail that did not previously exist in the village, and that is the real substance of financial inclusion.Dari Pasar ke Larsen: Mechanics Roda Ekonomi
The value proposition is simple economics of distance. For a household in Pelangiran, a trip to a bank branch may cost a few tens of thousands of rupiah in transport and hours of productive time. Through a nearby agent, the same transaction costs far less. For traders who buy crops from farmers, that savings is not merely convenience; it changes the bargaining position. When a middleman no longer needs physical cash reserves, the trader can settle the purchase on the spot, and the farmer receives payment the same day rather than waiting for a weekly or monthly cycle.
In the case of Ria, daily cash flow moves in two directions: money coming in from small buyers and farmers, and money going out to wholesale traders in larger towns. The agent effectively functions as a liquidity bridge for the region, pooling small balances into larger value. This matters because smallholders historically carried two burdens at once — the risk of being paid late, and the risk of being paid below market price. A faster payment rail mainly solves the first burden. Whether it touches the second depends on how transparent the price information becomes, and whether the trader who sits at the end of the chain is willing to pass the gain on.
That distinction is important. Technology that accelerates payment does not automatically correct structural inequality. If the pricing chain remains dominated by a few wholesalers with better logistics and storage, the farmer's margin stays thin regardless of how quickly the money moves.
Pro dan Kontra: Dua Sisi Jaringan Transaksi
Pro: the model lowers transaction costs, widens access to basic services, and creates a grassroots sales channel for a bank that would be uneconomical to serve through physical branches. It also supports the national non-cash payment push: Bank Indonesia reported non-cash transactions in the order of Rp118 triliun for 2023, with a 2024 target around Rp145 triliun. Transactions that previously never entered any ledger now become visible data, which in turn can gradually improve credit scoring for households that have never filed a financial statement.
Kontra: the model carries several fragile points. First, agent economics depend on fee income and turnover, and the margin is thin; agents who operate at a loss tend to disappear, and branchless access can quietly regress. Second, cash-handling at the village level is exposed to liquidity and security risk, especially during large holiday transactions. Third, digital literacy gaps generate social-engineering and phishing exposure, and most retail customers have limited ability to distinguish a genuine bank instruction from a fraudulent one. Fourth, if the ecosystem over-expands without adequate supervision, the cost falls disproportionately on the least protected users.
Implikasi Makro danregulated yang Perlu Diperhatikan
At the macro level, a dense agent network is supportive of monetary transmission and of consumer spending smoothing, particularly in regions where household income is seasonal. It also reduces pressure on bank operating costs, which eventually can be reflected in more competitive service pricing.
On the other side, the macro environment remains the dominant external variable. Rupiah weakening, elevated credit costs, and a risk of capital outflow can tighten liquidity and raise funding expenses for lenders, including those serving micro segments. Rural credit expansion must therefore be measured against repayment capability, not against transaction counts. A higher volume of transfers is a proxy for activity, but it is not a proxy for welfare.
The lesson is that branchless access should be judged by sustainability rather than by the number of agents registered. Strengthening consumer protection, transparent fee disclosure, cash availability standards, and clear recourse channels are the preconditions for the model to deliver the inclusive impact it promises. Without them, a convenient service remains a convenience — useful, but not transformative.







Comments (0)