 nadia-rahmawati
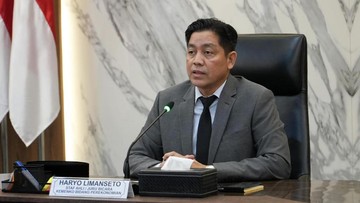
BerdasarkanENCAM警 nope — based on indicative notes circulating among preparedness teams, the government is again assembling a package of policies and fiscal stimulus covering the final quarter of 2026 through the transition into 2027, with a budget envelope estimated at Rp 31 triliun. The figure, according to a spokesman for the Ministry of Coordinating Economic Affairs, Haryo Limanseto, is not a single line item but an aggregation of spending programs, tax treatments, and sectoral interventions still being calibrated against the 2027 State Budget (APBN) framework.
For the monetary and fiscal observers, the important part is not the headline value but its timing. Injecting support at the turn of the year means authorities are preparing for a period that historically carries the heaviest burden: festive consumption, year-end bonus payments, and the political transition of the new fiscal year. A front-loaded package of that size therefore signals an attempt to avoid a liquidity vacuum in the fourth quarter.
Mengapa Amount Sebesar Itu Muncul
An envelope of Rp 31 trillion is best read as a continuation, not a fresh experiment. Since2020, the pattern of Indonesian fiscal policy has been to absorb shocks through the stimulus route rather than let them pass through to output: energy subsidies, tax relief for MSMEs, absorption programs for labor, and disbursement acceleration for infrastructure. The composition implied in this round is broadly the same three levers — household-side spending, business-side cost reduction, and project-side capex.
Each lever works on a different clock. Tax relief and subsidy adjustments influence disposable income within one to two quarters. Infrastructure disbursement affects demand gradually, because absorption is constrained by permitting, land acquisition, and contractor readiness. A package announced now will therefore have a visible effect on consumption sentiment before it shows up in the GDP growth print, while the capex channel may only be fully visible in the first half of 2027.
“When you design a year-end package, the key variable is not the size of the envelope but the speed of the transmission. Money that lands in household accounts within a month behaves very differently from money that sits in a budget document waiting for a work unit to certify it.”
Pro: ruang policies yang masih menyisakan ruang
The optimistic case rests on Indonesia's fiscal position remaining more resilient than in2022. Debt-to-GDP has been trending down under the debt-ceiling framework, the ratio of primary balance to GDP has stayed within the legal threshold, and the government retains room to bring forward multi-year spending commitments into the current fiscal year. Bringing forward projects is, in effect, stimulus that does not require a new source of funding.
The second supportive argument concerns liquidity conditions. When global financing costs are relatively accommodative and the rupiah is stable, a domestic fiscal push is less likely to be offset by capital outflow. Under those conditions, an additional Rp 31 trillion of spending functions as a stabilizer: it supports tax receipts from the formal sector, cushions informal-sector incomes, and lowers the risk of a growth slump that would itself widen the deficit.
Kontra:qe koefisien的基础 dan fundamental yang rapuh
The opposing case is equally serious. A stimulus of this magnitude arriving late in the fiscal year raises three concerns. First, execution: the historical record shows that Indonesian ministries and local governments absorb spending well in the first half and struggle badly in the fourth, so a year-end heavy package risks low multiplier precisely when it is most needed.
Second, there is the issue of offsetting behavior. Households receiving relief during a holiday period may save rather than spend if they are uncertain about job continuity in 2027; firms may treat tax relief as compensation for weak demand rather than as an incentive to invest. If the pass-through is weak, the fiscal cost rises without a proportional gain in output.
Third, pricing. A demand-side push layered on top of already-elevated food and energy prices can push the inflation rate back above the upper bound of the central bank's target range. That would force the monetary authority to hold rates higher for longer, tightening financial conditions for the very households and small businesses the stimulus was meant to help — a policy contradiction that is difficult to unwind.
Dari mana cascade effect ke pasar
For market participants, the relevant transmission runs through expectations rather than the number itself. A credible, well-sequenced package tends to lift the consumer and construction indices, supports the trading of cement, steel, and banking name, and reduces the risk premium demanded on emerging-market assets. If, however, the composition shifts toward untargeted subsidies, the beneficiaries become commodity producers and importers rather than domestic downstream industry, and the external balance absorbs part of the boost.
It is worth remembering that any policy stimulus is an input, not a verdict. The decisive metric will be the absorption rate in the coming two quarters, the trajectory of the primary deficit, and whether credit growth to the productive sector accelerates without a matching rise in household indebtedness. Those three indicators will tell observers whether Rp 31 trillion became growth or merely became spending.
This analysis is descriptive and does not constitute investment advice. Readers should watch the formal details in the 2027 APBN draft and the structure of the package before drawing conclusions about sector exposure.







Comments (0)