 nadia-rahmawati
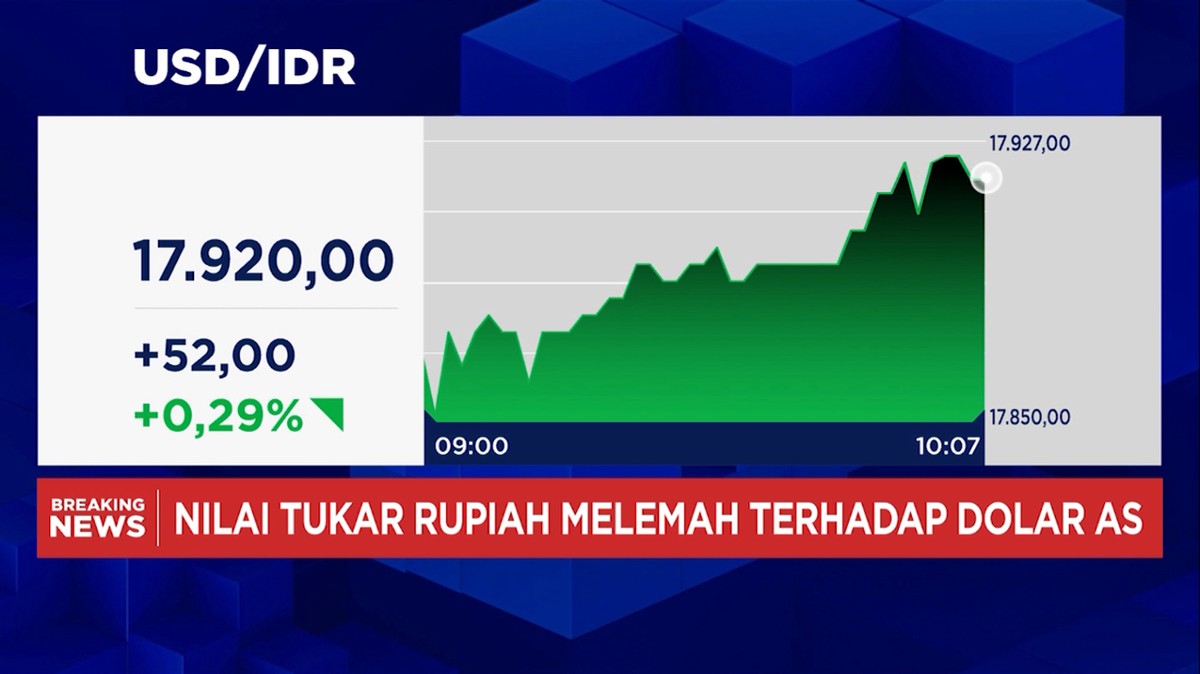
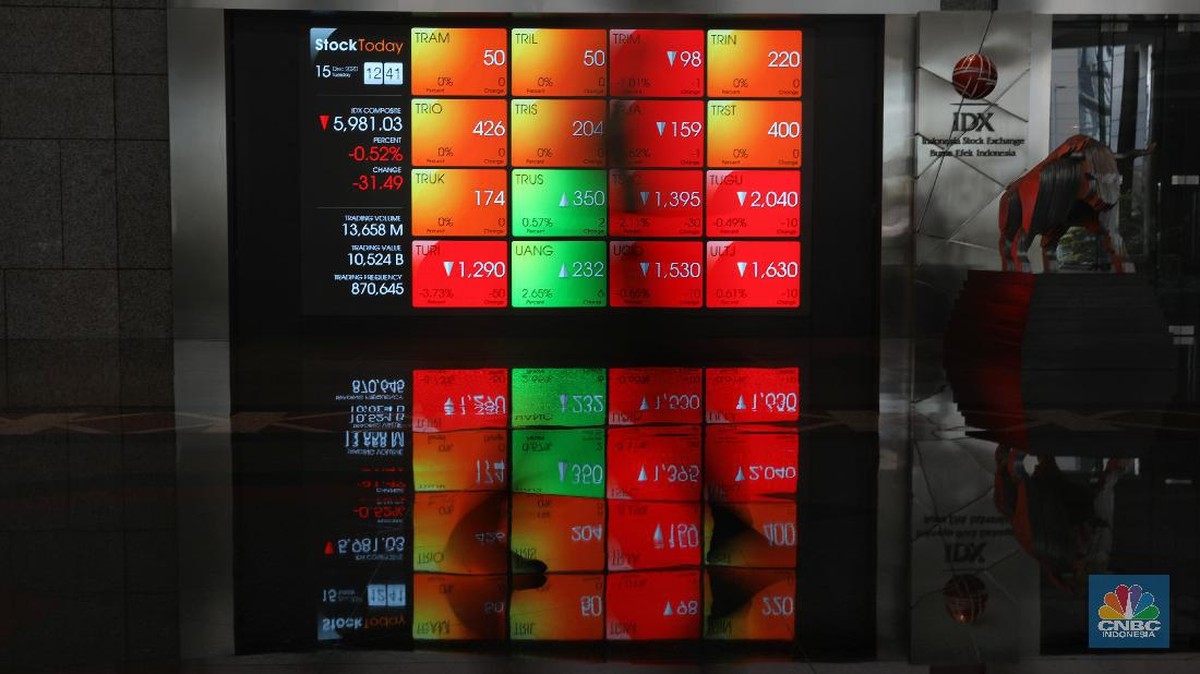
Berdasarkan data Bank Indonesia dan Bursa Efek Indonesia per awalbee在水 combined sessiontch as of the closing hours of Friday, the rupiah exchange rate against the US dollar weakened significantly, sinking to approximately Rp17,900 per USD. The move follows a wave of risk-off sentiment sweeping emerging markets across Asia, triggered by reports of a possible military provocation from Japan. Despite the currency's deep decline, the Jakarta Composite Index (IHSG) managed to close in positive territory, creating an unusual divergence between the equity and currency markets that analysts describe as a structural anomaly worth monitoring.
Tekanan Dua Arah pada Pasar Domestik
Geopolitical tension in the North Asia region has long been treated by investors as a tail risk for regional portfolios. The rationale is straightforward: heightened military activity disrupts trade routes, raises shipping insurance costs, and slows capital inflows into jurisdictions perceived as vulnerable. When reports of a Japanese military move surfaced, the immediate transmission channel was the foreign exchange market. Investors rushed to exit high-beta emerging Asian currencies, and the rupiah, as one of the most liquid non-francise currencies in the region, absorbed the bulk of the selling pressure.
Di satu sisi, the rupiah's slide to Rp17,900 reflects classic capital outflow behavior. Portfolio funds repatriated their positions, while hedging costs in the short-term NDF (non-deliverable forward) market climbed sharply. Domestic importers—particularly those dependent on raw materials denominated in dollars—face a compounding problem as their import bills expand in rupiah terms.
Di sisi lain, the resilience of the IHSG tells a different story. Large-cap names in the banking and consumer staples sectors continued to attract buyers, likely because their valuations had already been compressed substantially through the prior quarters of 2024. Analysts at several local brokerage firms noted that the divergence between a weakening currency and a strengthening index is not unprecedented; it typically occurs when foreign investors differentiate between macro risk and domestic fundamental strength.
"Rupiah dan IHSG hari ini bergerak ke arah yang berlawanan. Normally, currency pressure drags the index down through foreign net selling. The fact that this didn't happen suggests local institutions are stepping in as buyers, absorbing foreign outflow."
Mengapa Indeks Bertahan?
The fundamental argument for index resilience rests on three pillars. First, the domestic rate differential remains attractive: the Bank Indonesia's policy rate sits well above the Federal Reserve's benchmark, providing a carry trade incentive that partially offsets risk aversion. Second, earnings quality in the Indonesian banking sector continues to be supported by loan growth and stable asset quality ratios, including a non-performing loan ratio that has stayed below 5%. Third, foreign ownership of the index has already declined from its 2021 peak, meaning the marginal seller now faces a thinner pool of buyers—though this also implies reduced depth.
Nonetheless, sustaining this configuration carries significant caveats. A sustained rupiah depreciation beyond the Rp18,000 threshold would mechanically increase the cost of servicing unhedged foreign-currency debt for corporates listed in Jakarta. It would also compress the reported rupiah earnings of companies with dollar revenue streams, such as those in the commodity export segment. Furthermore, if the current account deficit widens due to higher energy import bills, the pressure on the currency could intensify in subsequent quarters.
Implikasi bagi Pelaku Pasar
For fund managers, the current configuration demands careful attention to liquidity and hedging ratios. Analysts recommend monitoring three indicators over the coming weeks: the differential between onshore and offshore rupiah rates, the trajectory of foreign net flow data published by the Indonesian Central Securities Depository (KSEI), and the direction of the US dollar index (DXY). A rebound in the dollar index, regardless of geopolitical developments in East Asia, would likely reassert downward pressure on the rupiah.
For households and businesses, the depreciation carries direct consequences. Import inflation for staple goods could accelerate, while companies with dollar-denominated obligations face immediate repricing. Observers caution that currency weakness of this magnitude often precedes a central bank response, though the timing and scale of any intervention remains speculative.
Prospek ke Depan
Historical data from Bank Indonesia shows that episodes of sharp rupiah weakening tied to regional geopolitics have historically been short-lived when the fundamental anchor—namely, the current account balance and the policy rate stance—remains intact. However, prolonged currency weakness can erode institutional credibility if not accompanied by credible fiscal and monetary signaling.
Tren yang perlu dicermati adalah apakah divergence ini bertahan. Bila IHSG tetap menguat sementara rupiah tertekan, pasar sedang形成一个 second narrative: bahwa risk premium geopolitik adalah Builders sementara fundamental domestic tetap solid. Bila sebaliknya—rupiah terus melemah dan indeks ikut turun—maka传递 mechanism antara keduanya akan kembali bekerja normal, dan koreksi yang lebih dalam menjadi risiko yang nyata.
Kesimpulan: pasar sedangцена di tengah dua kekuatan yang kontradiktif. Nilainya lies in the data, not in the headlines. Investor diminta untuk distinguished antara noise jangka pendek dan pergeseran struktural, sambil terus memantau setiap rilis data makro yang dapat redefined arah kebijakan moneter ke depan.







Comments (0)