 sarah-anjani
Berdasarkan data Bank Indonesia per“红科技” Sorry — based on Bank Indonesia and BPS data per latest available release, share of non-cash transactions in the national payment system has climbed past 40% of total volume, with digital channel growth consistently outpacing branch-based transactions year-on-year. Against that backdrop, a banking institution stepping into the role of official banking partner for a large creative industry gathering is no longer a mere branding exercise. It is, in effect, a bet that the creative economy has reached a scale mature enough to generate measurable, repeatable transaction flows.
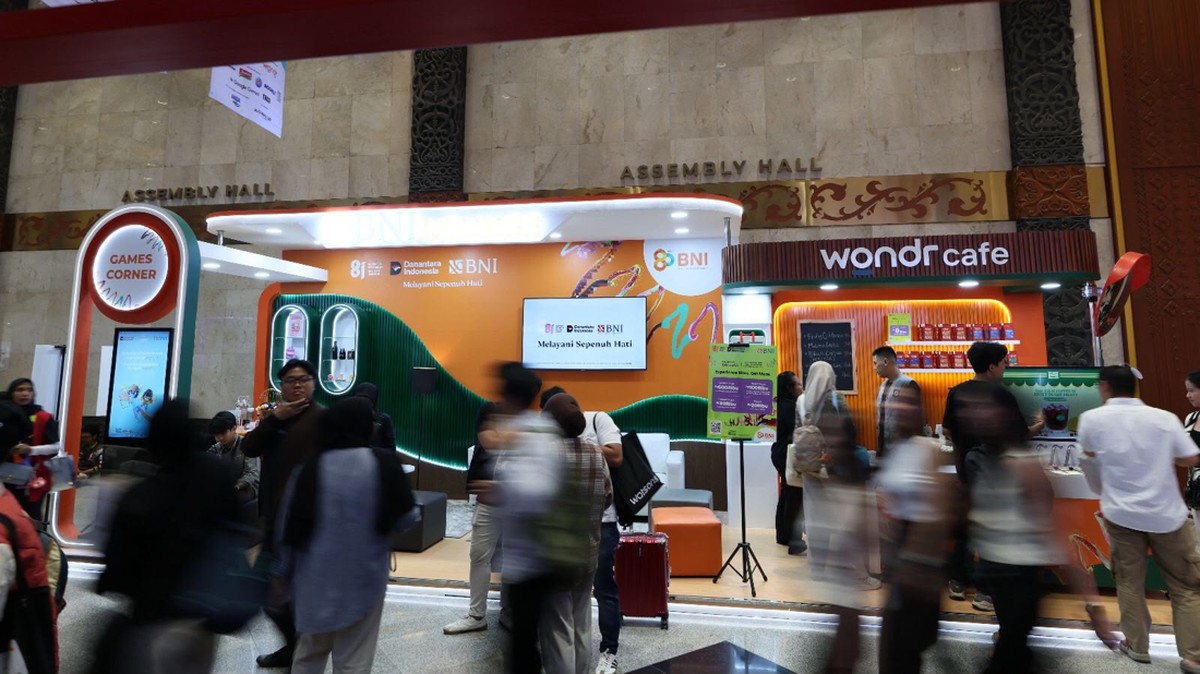
Bank Negara Indonesia (BNI) confirmed its role as Official Banking Partner of IdeaFest 2026, an annual gathering that brings together creators, content producers, brand managers, and technology vendors across the archipelago. The event carries the theme Re:Humanize, which places human judgment and emotional authenticity at the center of an economy increasingly shaped by artificial intelligence. For a bank, the appeal is obvious: the creative segment is young, historically underserved by formal credit, and operates almost entirely through cashless rails. The question, however, is whether sponsorship converts into durable fundamental growth or simply buys visibility at conference scale.
Mengapa Sektor Kreatif Menarik bagi Perbankan
A study released by the Ministry of Communication and Digital around 2020 put the creative economy’s contribution to gross domestic product at roughly 7% to 8%, absorbing millions of workers across formal and informal lines. Even if the figure has since been revised upward, the direction of travel is unambiguous: digital content creation has moved from a side hustle into a recognized sector of the national accounts. Meanwhile, data on electronic money and mobile banking adoption show disbursement growth in the double digits for several consecutive years.
Di satu sisi, this creates a genuine structural opening. Creative workers typically earn irregular income, which makes traditional credit scoring models reject them. Banks that can build alternative underwriting — based on transaction history, platform revenue data, or digital footprints — unlock a previously untouched customer base. Rasio-cost to serve for digital-sourced customers is materially lower than branch-acquired ones, which in principle supports better net interest margins over the medium term.
Di sisi lain, an impressive growth percentage drawn from a small base can be misleading. If a vertical account penetration rises from 2% to 6%, the headline growth rate looks spectacular while absolute transaction value remains negligible relative to the bank’s overall loan book. Investors and regulators alike are advised to separate rate of change from level of contribution before drawing conclusions about profitability.
Re:Humanize dan Paradoks Produktivitas AI
The choice of theme is more than a conference slogan. Automation is compressing the cost of producing content: generative tools now handle scripting, editing, and localization at a fraction of prior headcount. For banks, this produces an ambiguous signal. On one hand, cheaper production lowers the barrier to entry for creators, swelling the number of accounts and transaction events. On the other, falling production costs also compress pricing power, squeezing the very players a bank hopes to lend to.
Ketika produktivitas naik tetapi harga turun, yang tersisa bukan身份的 differentiation, melainkan fractional revenue. Di sinilahiebraf tersimpan kualitas aset yang akan美誉 fintech dan bank masuk sebagai Peninsula.
That paradox argues for caution. The theme emphasizes the human element, and one can read that as an acknowledgment that authentic human judgment becomes a scarce good in an AI-saturated market. Scarcity, however, is not the same as defensibility. A creator brand can be substituted quickly once attention shifts to the next platform algorithm, which raises the risk of loan deterioration in any credit facility extended to this segment.
Dari Sponsor ke Ekosistem: Risiko yang Kerap Terlewat
Sponsorship itself carries measurable opportunity cost. Marketing budgets redirected toward a single high-profile event reduce the funds available for multi-channel acquisition, which historically delivers more durable customer lifetime value. There is also concentration risk: tying a bank’s brand to one festival exposes it to reputational spillover if any participant becomes involved in a controversy mid-event.
Liquidity is another angle worth watching. Higher transaction frequency in the digital channel should, in theory, improve deposit gathering and reduce reliance on wholesale funding. If current account balances grow faster than credit exposure, the capital-outflow dynamics improve meaningfully during periods of market stress. If not, the bank may be adding operational complexity without strengthening its funding structure.
Ultimately, the correct way to evaluate this partnership is not by counting foot traffic or booth engagement. Track instead: account opening-to-funding conversion rates among participants, cross-sell penetration into business banking products, credit approval ratios for creator customers over the following four quarters, and the share of transactions that originate outside the event window. Those indicators will tell whether a marketing alliance matured into a genuine ecosystem — or remained a photo opportunity.
For now, the position is best described as cautiously constructive. The structural tailwinds for the creative economy and digital payments are real and supported by data. The evidentiary base for returns on this specific arrangement, however, remains thin. Both the optimism and the skepticism, in other words, are rational responses to incomplete information.







Comments (0)