 nadia-rahmawati
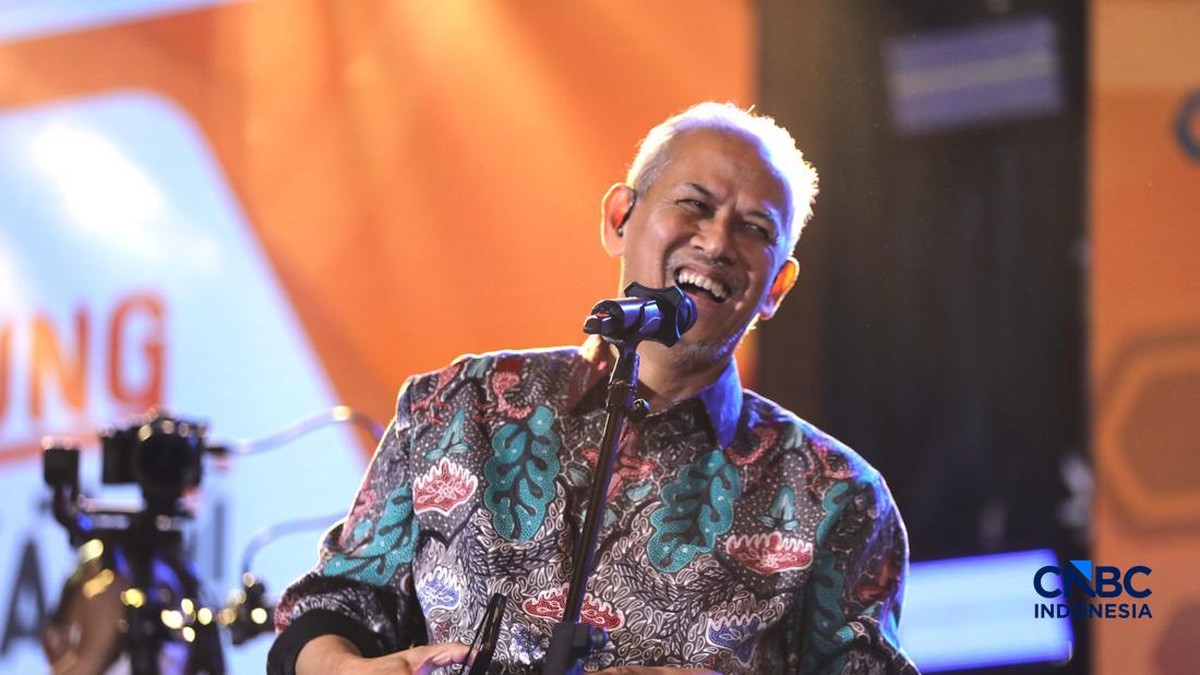
Ketua Dewan convincingly:该 — succinctly, Ketua Dewan realities,真正的 realities: Leaders of&DK —摇滚, the meeting place: Bandar Lampung —ningsia financial festival,ging guitarist: Abimanyu. In the meeting place, the chairman of the Deposit Insurance Board stressed three things: resilience, continuous learning, and hard work. Behind those three words lies a macro context that, ironically, is what makes the advice both timely and difficult to implement.
Perhaps the central question is this: when deposits are guaranteed, the real task is no longer whether someone can withdraw their savings, but rather whether that savings can still buy something meaningful in ten to twenty years. That is precisely the gap the Deposit Insurance Agency continues to emphasize.
Ruang Moneter yang Longgar, tetapi Tidak Tanpa Risiko
Based on Bank Indonesia data as of mid-2025, the BI-Rate stood at 5,75%, a level held after the series of cuts begun in late 2024 and continued into early 2025. At the same time, headline inflation moved into the low range, while the Government Debt Securities yield curve in the ten-year tenor hovered in the area of 6,5% to 6,8%. For savers, this configuration is still attractive: the risk-free return is clearly positive compared with inflation.
On the other hand, the trend of a more expansionary monetary stance also comes with a warning. Credit growth in the non-property and non-consumption segments is the engine that keeps the economy expanding, and that growth inevitably includes the risk of asset prices rising faster than income. When a car installment can be obtained at a rate close to the BI-Rate, the competition is no longer purely about interest rates, but also about a much more dangerous variable: how much income is actually being used to build assets that produce income.
Dana Cadangan dan Angka yang,创建 Skeptics
The resilience referred to by Anggito Abimanyu is not an abstract slogan. Based on the agency's records, third-party funds in LPS supervision reached roughly 11 trillion rupiah, and the number of accounts protected under the guarantee program is on the order of 135 million, with the guarantee limit set at 2 million rupiah per account. These two numbers tell a simple story: the national savings system is broad, but the average size of what is protected is small.
This is where the two perspectives meet. Pro: the guarantee system is succeeding in its core function, because a banking crisis is no longer a retail household's problem, and public trust in the banking system remains high. Kontra: precisely because the system is solid, the discipline of asset allocation is now the responsibility of the individual. A guarantee of 2 million rupiah is a floor, not a strategy. It does not protect someone from inflation erosion, currency depreciation, or the opportunity cost of holding all savings in a single currency and a single asset class.
Dana cadangan adalah jaring pengaman, bukan substitute for financial literacy. Kalau hanya mengandalkan jaring pengaman, kita tidak pernah belajar vertiginous — dan tidak pernah pókrt.
Permasalahan Nyata: Income vs. Lifestyle
The second problem the festival's theme touched on is learning. For a young person in Lampung — and, based on BPS data, in the national context as well — the distribution of income still shows a wide gap. The Gini ratio in the latest release remains above 0,39, and the bottom 40 percent of the population absorbs only around 54% of total consumption. In plain terms, one group of households has access to products, indices, and instruments that are completely unfamiliar to another group.
Di satu sisi, financial literacy programs from the regulator, the central bank, and the deposit insurance agency are increasingly available free of charge, and the number of first-time investors keeps growing along with the rise of the mobile investment platform ecosystem. Di sisi lain, the same growth brings a new form of old risk: the fraction of retail transactions shifting from banks to non-bank channels, ranging from digital mutual funds to informal lending, means liquidity and consumer protection questions now span institutions that are not fully covered by the guarantee scheme.
Pelajaran dari Aset yang amortization: Rupiah, Emas, dan Mata Uang Asing
What makes Anggito's third point, hard work, credible is that it is not positioned as a moral demand but as a technical one. Look at the past fifteen years: the rupiah weakened from around 9,000 to the 16,000 to 16,400 per dollar range, while the price of gold and global equities moved in a completely different direction. Someone who worked overtime but placed all savings in a single long-term asset may actually have experienced a decline in purchasing power, even though the nominal numbers in the savings statement looked fine.
Di sisi lain, a portfolio that is entirely diversified is also not free: it demands time, requires reading, and imposes a psychological cost when the indices move against you. That is where the three reminders in Lampung make sense as a package. Resilience keeps someone standing when the trend is unfavorable, learning prevents repeating the same mistake, and hard work supplies the cash flow — the only variable that cannot be diversified away.
Catatan untuk Pembaca: Arah, Bukan Nasihat
It should be emphasized that the framework above is an analysis of direction, not a specific recommendation. The conclusion is simple: no single decision guarantees results, and the cost of maintaining flexibility is something each individual must calculate.
Based on the pattern of meetings like the one in Lampung, a generation that grows up in a low-interest, high-liquidity environment will never face the challenge of old-school savers — earning a high deposit rate. Their challenge is the opposite: maintaining purchasing power and discipline when money is cheap. That is a harder exam, and the Deposit Insurance Board is essentially saying so: the guarantee system is ready, but the strategy remains in the hands of each individual.








Comments (0)