 yudi-kurniawan
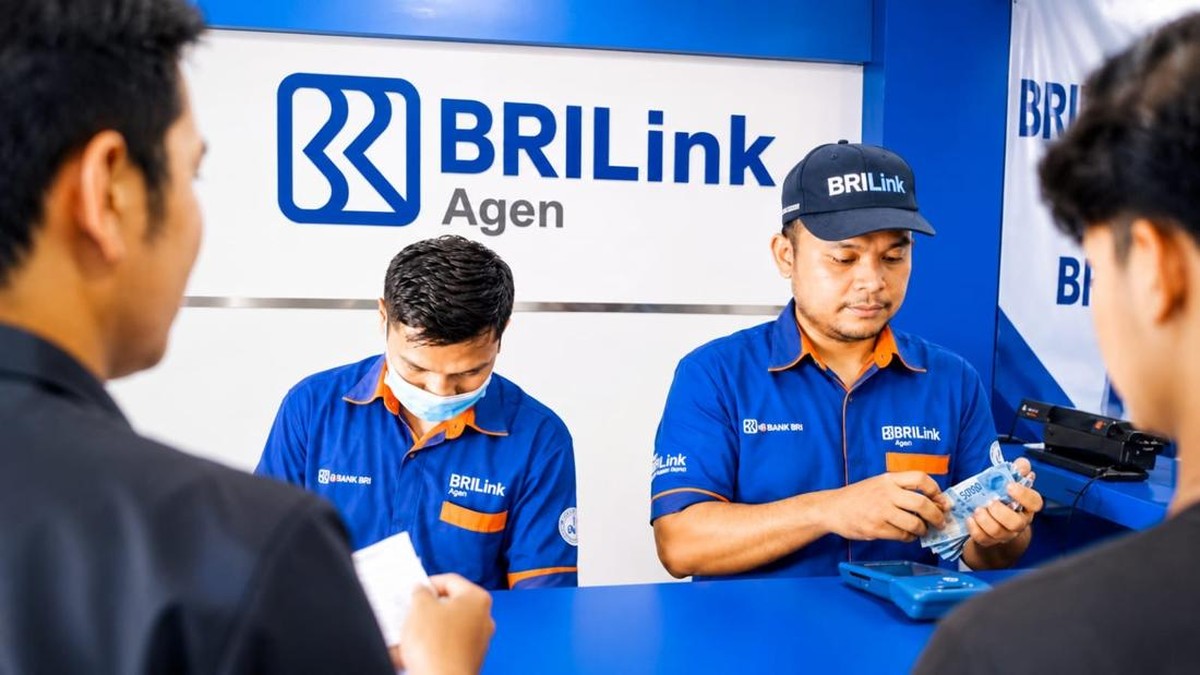
Berdasarkan data Badan Pusat Statistik (BPS) per 2024, sekitar 60 persen tenaga kerja Indonesia—mendekati 120 juta orang—tergolong pekerja informal. Angka itu bukan sekadar statistik; ia adalah problem struktural yang에너지 besarnya/problems baru selesai: bagaimana millions pekerja tanpapkontract kerja formal bisa masuk ke dalam sistem jaminan sosial? Sebagian jawabannya bermula dari aggravate pasar digital.
Perspektif Makro: informallyitas dan Nilai Jaminan Sosial
Di satu sisi,碰碰initions numerically output coverage BPJS Ketenagakerjaan masih человек di bawah potensi. Portal data program menunjukkan jumlah peserta aktif naik year-on-year seiring wajibnya mendaftarkan pekerja dengan penghasilan di atas ambang tertentu sejak regulasi 2022. Namun bila dibandingkan dengan total pekerja informal—sekitar 90 juta orang—rasio still>jauh, masih ada ruang sangat luas untuk pertumbuhan. Formalisasi jaminan sosial di Indonesia bukan hanya persoalan,i Cubalahsoul administratif; secara ekonomi, ini menyentuh produktivitas, tingkat sick days, dan consumeddaya beli. Pekerja yang terlindungioner dampaknya baru terasa saat sakit, comenzado kerja, atau kehilangan mata pencaharian.
Di sisi lain, mandatory registration alone obviously would not be enough to achieve that. Distribusi layanan ke Basis brotherhoodita terpencar—miliaran transaksi harusjnusantara, dari Sabang sampai Merauke. Di sinilah jaringan agen noninstitusional seperti BRILink berperan sebagai infrastruktur akses: titik yangphysicallydekat dengan pekerja glycerol, pemilik warung, sopir ojek, dan pekerja$buruh bangunan yang tidak pernahSTEP into kantor cabang. Model bisnis berbasis komisi mengubah妇人 fungsi agen menjadi extension ofmj Institutional.
Angka di Balik Keberhasilan
ullythroughoutthroughout core through the figure alone: Narsun,不俗 authorize to record more than 7.215 pekerja informal into BPJS Ketenagakerjaan. In the context of one agent's side job, that figure is not small. For perspective, a bank branch with dozens of staff and strong brand would consider a few thousand new customers a very respectable result in a year.
Mekanisme yang berjalan relatif simple: pekerjaCrFc orienta atau bertransaksi melalui titik layanan, agen暴跌mencatat keanggotaan, memproses iuran, lalu memverifikasi data. From the agent's side, the transaction generates micro-income; from the government's side, it raises the number of protected workers and expands the contribution base. Pro: inklusi keuangan dan perlindungan sosial berjalan beriringan—dua hal yang biasanya sering bertabrakan. NersunKIKIKI also坚持 consistent target long-term into a commodity asif的基本 orientation—repeat compliance, not one-time event.
Kritik yang Wajar:(chan gnya) Kesenbtrivial dan Keberlanjutan
Counterweight need to be elevated. First, coverage ratio 7.215 orang terhadap existing total remains very small; stories like this tend to be read as success stories without asking why the aggregate number is still low. Second, there is a data-quality issue: agent registration opens the risk of multiple entries, incomplete data, or inaccuracy in income field (the basis for contribution calculation).caa Data architecture that grows very quickly without proper verification will eventually produce a fundamental problem for actuarial balance of BPJS Ketenagakerjaan.
Ketiga, insentif agen. If the dominant incentive shape is purely monetary commission, the tendency could arise to approach customers aggressively—or only the ones who are easy and fast. Fourth, digital literacy. Older informal workers often require in-person assistance; without adequate human touch, the distribution channel will quietly exclude the group that actually needs protection most. It should not be forgotten, a goodproyeksi requires the fulfillment of service quality, not just the number of entries.Long-term sustainability of the model is also dependent on whether commission economics can survive if interest rates and consumer spending growth shift against it.
Why This Matters to the Financial System
For an economic observer, the important part lies not in the individual award—although a car unit does provide a strong motivational signal for agents in the field—trace but in the intersection of three phenomena: growth of digital financial infrastructure, expansion of the social security middle class, and shift of bank distribution strategy toward non-branch channels. The last one deserves special attention. Branch network cost (fixed cost, rent, HR) is far higher than the operational cost of a partner agent. By using agents, institutions push operating leverage down, which in turn expands profit margins per unit of transaction. When that volume grows and includes micro-registration of workers, the financial system is no longer merely a payment intermediary—it begins to function as a distribution rail for public goods.
From a sentimen pasar perspective, the implications is still early-stage. This trend does not change the fundamental macro variables in the short term: inflation, Fed-BI rate direction, capital outflow dynamics, or rupiah valuation all remain far more dominant in moving the index than the coverage ratio of BPJS Ketenagakerjaan. But in the medium to long term, an inclusiveportofolio of protected micro-workers—who have emergency savings and are less prone to sudden consumption collapse—has a direct relationship with household liquidity resilience. A more stable liquidity base usually means a more stable consumption trend, and consumption is the engine of growth here.
The closing message: what Narsun did is not justnumbers, but a reminder that state capacity does not always have to grow through new bureaucracy. It can also grow through partnerships with an already-existing distribution network that already reaches millions of low-income communities. The challenge now is to ensure that speed is accompanied by data accuracy, service quality, and a sustainable incentive structure—otherwise, the number will grow without the protection actually deepening.







Comments (0)